FHA Loan vs Conventional Loan: Which One Costs Less?
 10.16.2026
FHA loans let you buy with a lower credit score and as little as 3.5% down, but the mortgage insurance usually stays for the life of the loan. Conventional loans require stronger credit, but their mortgage insurance can be canceled, so they usually cost less for borrowers with strong credit.
Most buyers can qualify for both loans. The better pick depends on three things: your credit score, your down payment, and how long you plan to keep the home.
This guide compares the FHA home loan and the conventional loan on real costs. You’ll see a worked payment example on a $350,000 home, how underwriters review each loan, and a checklist to finish.
What is the difference between an FHA loan and a conventional loan?
An FHA loan is insured by the Federal Housing Administration, so lenders take less risk and can approve borrowers with lower credit scores. A conventional loan has no government insurance and follows Fannie Mae and Freddie Mac guidelines.
FHA rules come from HUD Handbook 4000.1. Conventional rules come from the Fannie Mae Selling Guide and the Freddie Mac Guide. A lender like Rize Mortgage can offer both.
Lenders can also add their own stricter rules, called overlays. That means the official minimum and a lender’s actual minimum are often different numbers. You can ask for both.
FHA vs conventional loan
FHA wins on credit flexibility, DTI room, and easier assumption. Conventional wins on cancellable mortgage insurance, higher base loan limits, and flexible property use.
| Criteria | FHA loan | Conventional loan |
|---|---|---|
| Minimum credit score | 580 for 3.5% down; 500–579 with 10% down | No fixed floor in Fannie Mae’s automated system since Nov. 2025; lenders and mortgage insurers set their own |
| Minimum down payment | 3.5% | 3% on eligible programs; 5% or more is common |
| Upfront mortgage insurance | 1.75% of the base loan | None in most cases |
| Ongoing mortgage insurance | Annual MIP, typically 0.55% | PMI, priced by score and down payment |
| How long it lasts | Life of loan if under 10% down; 11 years if 10% or more | Cancel at 80% LTV (request); ends automatically at 78% |
| Max DTI | Up to 46.9% / 56.9% with AUS approval; 31% / 43% manual baseline | Up to 50% with DU approval [VERIFY] |
| Loan limit (1-unit) | $541,287 in most counties; up to $1,249,125 in high-cost areas | $832,750 in most areas; up to $1,249,125 in high-cost areas |
| Occupancy | Primary home only | Primary, second home, or investment |
| Seller concessions | Up to 6% | 3%, 6% or 9% depending on down payment [VERIFY] |
| Wait after bankruptcy / foreclosure | 2 years (Ch. 7) / 3 years | 4 years (Ch. 7) / 7 years [VERIFY] |
| Assumable | Yes, with lender approval | Generally no |
Is an FHA loan easier to qualify for than a conventional loan?
Usually, yes. HUD allows scores as low as 580 with 3.5% down. Conventional loans have loosened too, but pricing gets steep as scores drop.
Fannie Mae removed its fixed 620 minimum for loans run through Desktop Underwriter in late 2025. That does not mean every lender will approve a low score. Lenders, mortgage insurers, and Freddie Mac programs can still set their own floors.
The bigger difference is price. FHA mortgage insurance does not change with your credit score, conventional PMI and rates do. That is why a 640 borrower often pays less with FHA, and a 740 borrower often pays less with conventional.
Underwriters also read the story behind the score. Recent late payments, new collections, and maxed-out cards can hurt more than the number itself. For the full FHA checklist, see our guide to FHA loan requirements.
FHA vs. conventional down payment requirement
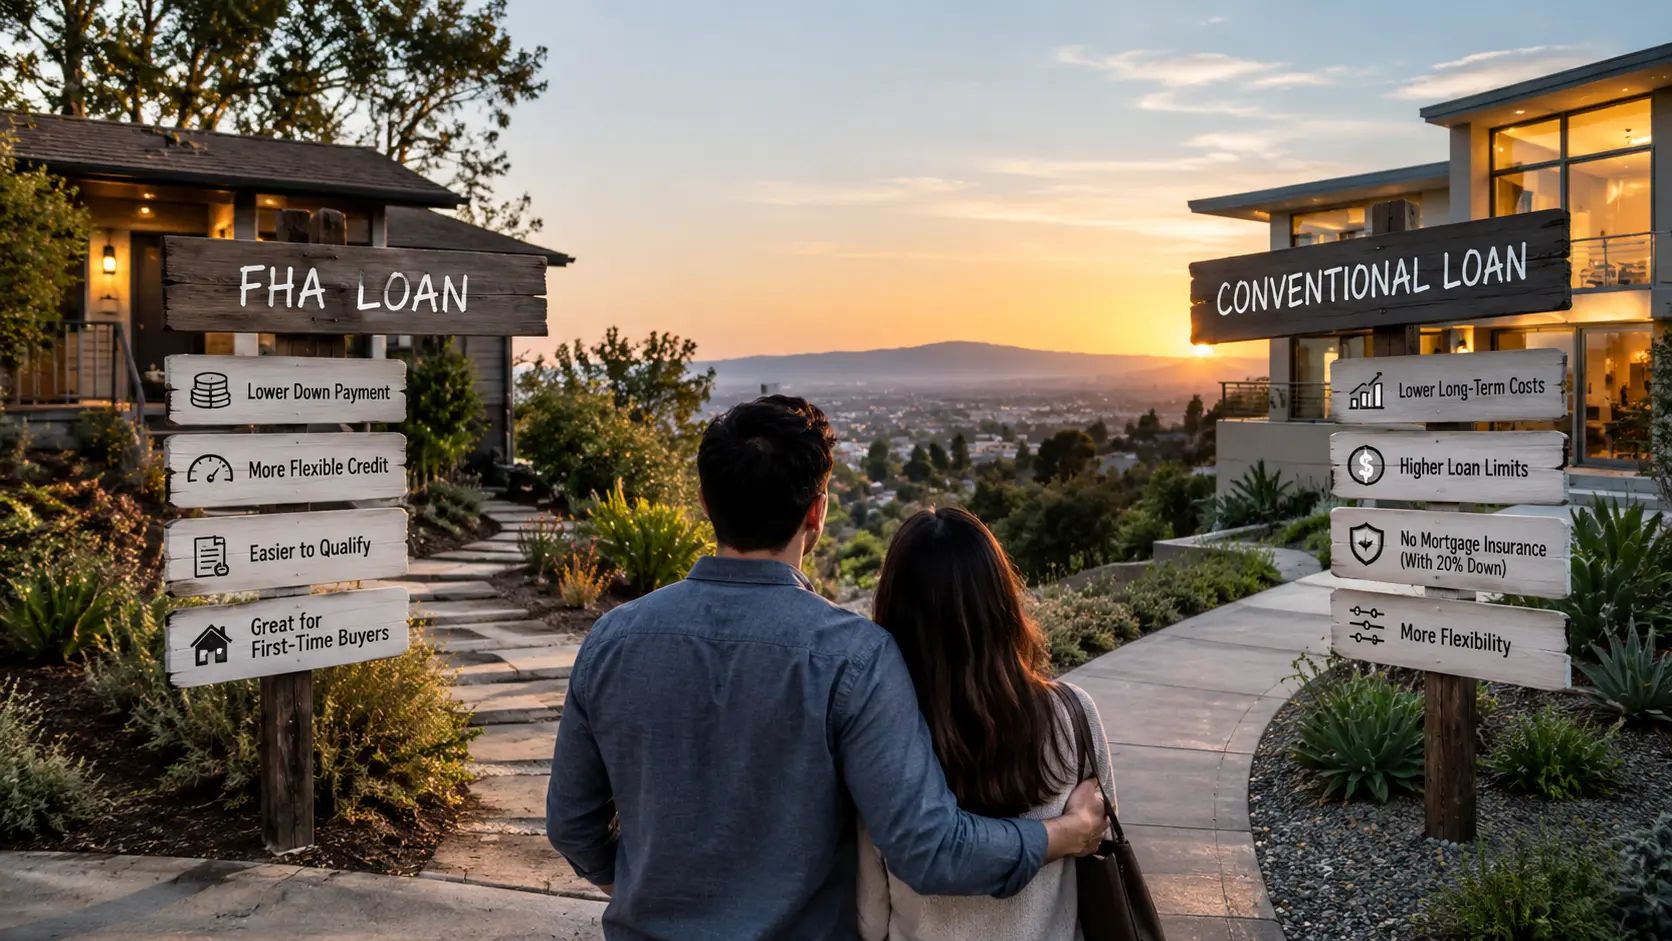
FHA requires 3.5% down. Conventional can go as low as 3% for eligible buyers, but many conventional borrowers put down 5% or more.
On a $350,000 home, that is $12,250 for FHA, $10,500 for a 3% conventional loan, and $17,500 for a 5% conventional loan. The 3% options, such as HomeReady and Home Possible, have rules like income limits, first-time buyer status, or homebuyer education.
Both loans allow gift funds with a gift letter. Underwriters will still trace where the money came from. Plan on two months of bank statements for the account holding your down payment.
How do mortgage insurance costs compare (MIP vs PMI)?
FHA charges 1.75% upfront plus an annual premium, typically 0.55%. Conventional PMI usually has no upfront fee, and its price depends on your credit score and down payment.
On FHA, the upfront premium is usually rolled into the loan, which raises your balance. Annual MIP is paid monthly. Conventional PMI is priced by risk, so strong credit can cut it sharply.
Does FHA mortgage insurance ever go away?
Only in some cases. With less than 10% down, FHA MIP lasts for the life of the loan. With 10% or more down, it drops off after 11 years. The usual way out of lifetime MIP is a refinance into a conventional loan once you have enough equity and credit.
Can you cancel conventional PMI?
Start your mortgage journey with clear guidance and real numbers. See what you qualify for today.
Yes. You can ask to cancel PMI when your balance reaches 80% of the home’s original value. It ends automatically at 78% if you are current on payments. This comes from the Homeowners Protection Act. Servicers may require a good payment history and sometimes an appraisal.
Which loan has the lower monthly payment?
It depends on credit. In the example below, the 640-score borrower pays about $272 less per month with FHA, and the 740-score borrower pays about $73 less per month with conventional.
Assumptions: $350,000 purchase price, 30-year fixed.
- FHA: 3.5% down, 6.00% rate, 1.75% upfront MIP financed, 0.55% annual MIP.
- Conventional, borrower A (640 score): 5% down, 6.50% rate, 1.40% PMI.
- Conventional, borrower B (740 score): 5% down, 6.125% rate, 0.45% PMI.
Taxes, homeowners insurance, and HOA dues are excluded because they are similar on both loans.
| FHA (3.5% down) | Conventional, 640 score (5% down) | Conventional, 740 score (5% down) | |
|---|---|---|---|
| Down payment | $12,250 | $17,500 | $17,500 |
| Base loan | $337,750 | $332,500 | $332,500 |
| Upfront MIP (financed) | $5,911 | none | none |
| Final loan amount | $343,661 | $332,500 | $332,500 |
| Rate | 6.00% | 6.50% | 6.125% |
| Principal & interest | $2,060 | $2,102 | $2,020 |
| Monthly mortgage insurance | $158 | $388 | $125 |
| P&I + mortgage insurance | $2,218 | $2,490 | $2,145 |
The monthly gap is only part of the story. Borrower B’s PMI can be removed when the balance reaches 80% of the original value, about 10 years on the regular schedule in this example. Borrower B’s FHA MIP would keep going. That is why a strong-credit borrower’s lead on conventional tends to grow over time.
Borrower A’s FHA win is bigger and happens right away. FHA also needs $5,250 less cash down in this example. Run your own numbers with our mortgage calculator.
How do underwriters review FHA and conventional loans?
Both start with an automated underwriting system (AUS), then an underwriter checks your documents. If the automated underwriting system cannot approve the file, it may go to manual underwriting with tighter limits.
FHA files run through TOTAL Scorecard. Conventional files run through Desktop Underwriter or Loan Product Advisor. A few practical points:
- Automated underwriting system vs. manual: Manual FHA underwriting starts at 31% housing and 43% total DTI. Automated underwriting systems can approve much higher when the rest of the file is strong.
- Overlays: A lender can be stricter than HUD or Fannie Mae. This is why two lenders can give different answers on the same file.
- Large deposits: Both programs ask you to explain and document large, unusual deposits. The dollar trigger differs by program and underwriting method.
- Reserves and stability: Savings left after closing and steady income can offset a higher DTI.
Want to know where you stand? Try the home affordability calculator first.
What are the loan limits for FHA and conventional loans?
For one-unit homes, the FHA limit is $541,287 in most counties and up to $1,249,125 in high-cost areas. Conventional conforming limits start higher at $832,750 in most areas.
In a lower-cost county, a pricier home may only work with a conventional loan. Above the conforming limit, you would look at a jumbo loan. Limits reset every January, so check HUD’s lookup tool for your county.
Do FHA and conventional loans have different property rules?
Yes. FHA appraisals check that the home meets HUD minimum property standards for safety and soundness. Conventional appraisals focus on value and general condition.
An FHA appraiser may flag a leaking roof, exposed wiring, or broken stair railings. Repairs may be needed before closing. Ask your agent about the home’s condition before you write an offer. FHA is also for primary residences only. If you plan to rent the property out, look at investment property loans instead.
Which loan is better for you: FHA or conventional?
Choose FHA if your credit, debt, or cash is tight, and choose conventional if you have strong credit and want mortgage insurance you can drop. Being a first-time buyer alone does not point you to FHA, since 3% conventional options exist.
FHA often fits if:
- Your score is in the 600s, and conventional PMI would be expensive.
- Your monthly debts are high compared to your income.
- You had a bankruptcy or foreclosure within the last few years.
- You want a loan a future buyer could assume.
Conventional often fits if:
- Your credit is strong enough to earn low PMI pricing.
- You want PMI that can be cancelled.
- You are buying a second home or investment property.
- Your loan amount is above the FHA limit for your county.
Can you refinance an FHA loan into a conventional loan?
Yes, you can refinance an FHA loan into a conventional loan. You refinance into a conventional loan once your credit and equity are strong enough, and that is how most borrowers drop lifetime FHA MIP.
With 20% equity, a conventional refinance can skip PMI entirely. Count the closing costs and divide by your monthly savings to find your break-even point.
If you want to stay on FHA but lower your rate, look at an FHA streamline refinance. For other options, see rate-and-term refinance.
How can you compare FHA and conventional on your own numbers?
Ask a loan officer to price both loans using your credit, down payment, and debts on the same day. The better choice usually shows up in the monthly payment, the cash to close, and the cost of mortgage insurance over time.
Rize Mortgage offers FHA, conventional, VA, USDA, and jumbo loans, so you do not have to change lenders if the answer changes midway.
What should you do next?
- Pull your credit reports at AnnualCreditReport.com and fix errors.
- List every monthly debt and estimate your DTI.
- Decide your down payment and how much cash you can bring to closing.
- Gather two months of bank statements and document any gift funds.
- Ask for FHA and conventional quotes on the same day.
- Compare monthly payment, cash to close, and how long mortgage insurance lasts.
- Ask about the lender’s overlays.
- Check the FHA and conforming limits for your county.
- Get preapproved before you shop.
Conclusion
Choose an FHA home loan if a lower credit score, higher debt, or limited cash is your biggest hurdle. Choose a conventional loan if your credit is strong and you want mortgage insurance that can come off. If you can’t tell which side you’re on, compare both with your real numbers.
Neither loan is better for everyone. The same $350,000 home gave opposite winners in our example, and the only thing that changed was the borrower’s credit. That is why a general rule can only get you so far.
Ready to see your numbers? Talk to a loan officer at Rize Mortgage, or start your application to compare your FHA and conventional options in one conversation.
Is FHA or conventional better for first-time homebuyers?
Neither is better for everyone. FHA often helps first-time buyers with lower credit scores or higher debt, while conventional can cost less when credit is strong, including options with 3% down. Compare both quotes using your own numbers. The monthly payment and how long mortgage insurance lasts usually decide it.
Can I get a conventional loan with 3% down?
Yes, if you qualify for a program that allows it. Programs like HomeReady and Home Possible, and standard 97% loans for first-time buyers, allow 3% down.
These programs can have income limits, homebuyer education, or property rules. Mortgage insurance still applies, and its cost depends on your credit score.
Do FHA loans have higher interest rates than conventional loans?
Not always. FHA rates can be similar to conventional rates, but the FHA APR is usually higher than its interest rate because it counts mortgage insurance. Compare the monthly payment and APR, not just the rate. Your rate depends on your credit, down payment, and the market on the day you lock.
Can I get an FHA loan with a 600 credit score?
Yes, you can get an FHA loan with a 600 credit score. HUD’s minimum for 3.5% down is 580, so a 600 score can qualify. Some lenders set a higher minimum, so ask before you apply.
Is FHA or conventional better if I plan to sell in a few years?
It depends on your credit, but the upfront cost matters more on a short timeline. FHA charges a 1.75% upfront premium, while conventional usually has no upfront mortgage insurance fee.
Start your mortgage journey with clear guidance and real numbers. See what you qualify for today.