Bridge Loan Requirements: How to Qualify & Get Approved
You found the investment property you've been chasing for months with the right price, in the right neighborhood, and about to get snapped up by a cash buyer. Then your down payment is sitting in the equity of a property you haven't sold yet.
This is the exact situation bridge loans were built for. But before a lender hands you six or seven figures against equity, they need to know you can handle the loan responsibly. That means meeting a specific set of bridge loan requirements around credit, equity, income, and how you plan to pay it back.
This guide breaks down exactly what lenders look for, what documents you'll need, how much you can actually borrow, and the mistakes that get bridge loan applications denied. If you're trying to figure out the requirements for a bridge loan before you start shopping for one, this is the checklist to work from.
What Is a Bridge Loan?
A bridge loan is short-term financing, typically lasting anywhere from a few months to about a year, that uses the equity in a property you already own as collateral to fund the purchase of your next one. It bridges the gap between buying and selling.
Two groups rely on bridge loans most:
- Real estate investors who need to close on a new investment property fast without waiting for a current property to sell or a long-term loan like a DSCR loan to fund.
- Homeowners who want to buy their next home before listing and selling their current one, avoiding the stress of moving twice or making a contingent offer that sellers often reject in competitive markets.
Because the loan is secured by existing equity rather than the income the new property will generate, bridge loans move faster than conventional financing, but lenders still underwrite them carefully. That's where the requirements come in.
Bridge Loan Requirements
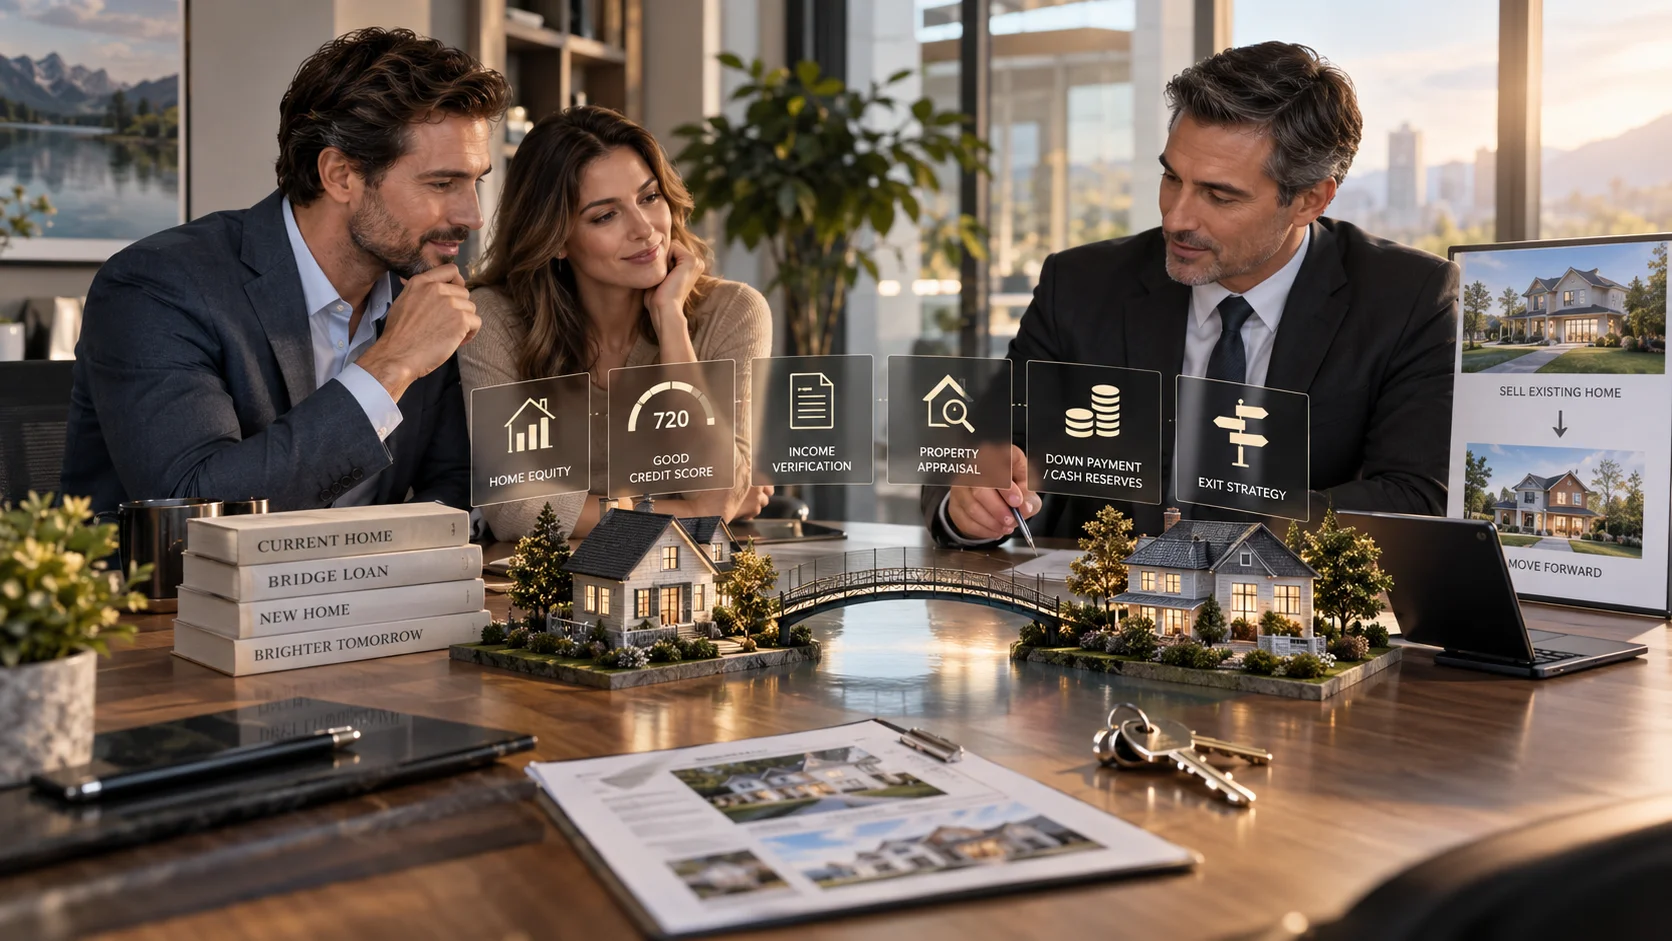
Every lender's guidelines differ slightly, but most bridge loan qualifications fall into five categories: credit, equity, debt-to-income ratio, income documentation, and paperwork. Here's what to expect in each.
Credit Score Requirements for a Bridge Loan
Bridge loans are considered higher-risk, shorter-term products, so credit score minimums tend to run higher than what you'd need for a conventional mortgage. Most bridge lenders want to see a credit score in the mid-600s to low-700s range, with stronger pricing and terms available above 700. A higher score won't just help you qualify; it typically reduces your interest rate and origination fees, since bridge loans already carry a rate premium over traditional financing.
If your score is borderline, paying down revolving balances or disputing reporting errors in the 60–90 days before you apply can move the needle.
How Much Equity Do You Need for a Bridge Loan?
Equity is the backbone of a bridge loan. Since the loan is secured against the value of your current property, lenders generally want to see at least 20–30% equity remaining after the bridge loan is originated. In practice, this is expressed as a maximum combined loan-to-value (CLTV) ratio, the total of your existing mortgage balance plus the new bridge loan, divided by your property's appraised value.
The more equity you have, the more borrowing power you unlock and the more comfortable a lender feels that a drop in your home's value or a slower-than-expected sale won't leave them exposed.
DTI Ratio Requirements for a Bridge Loan
Your debt-to-income (DTI) ratio still matters for bridge loans, even though the loan itself is short-term. Lenders typically want your DTI, including the new bridge payment (or its interest-only equivalent), to stay under 45–50%. Some lenders will exclude the payment on your existing mortgage from this calculation if that property is under contract to sell, since the debt is expected to disappear shortly after closing.
Income and Employment Documentation
Because you'll likely be carrying two properties and possibly two mortgage payments simultaneously for a period, lenders want confidence you can service both if the sale of your current property takes longer than planned. Expect to provide:
- Recent pay stubs or, for self-employed and investor borrowers, two years of tax returns and profit-and-loss statements
- W-2s or 1099s from the past two years
- Bank statements showing reserves
Start your mortgage journey with clear guidance and real numbers. See what you qualify for today.
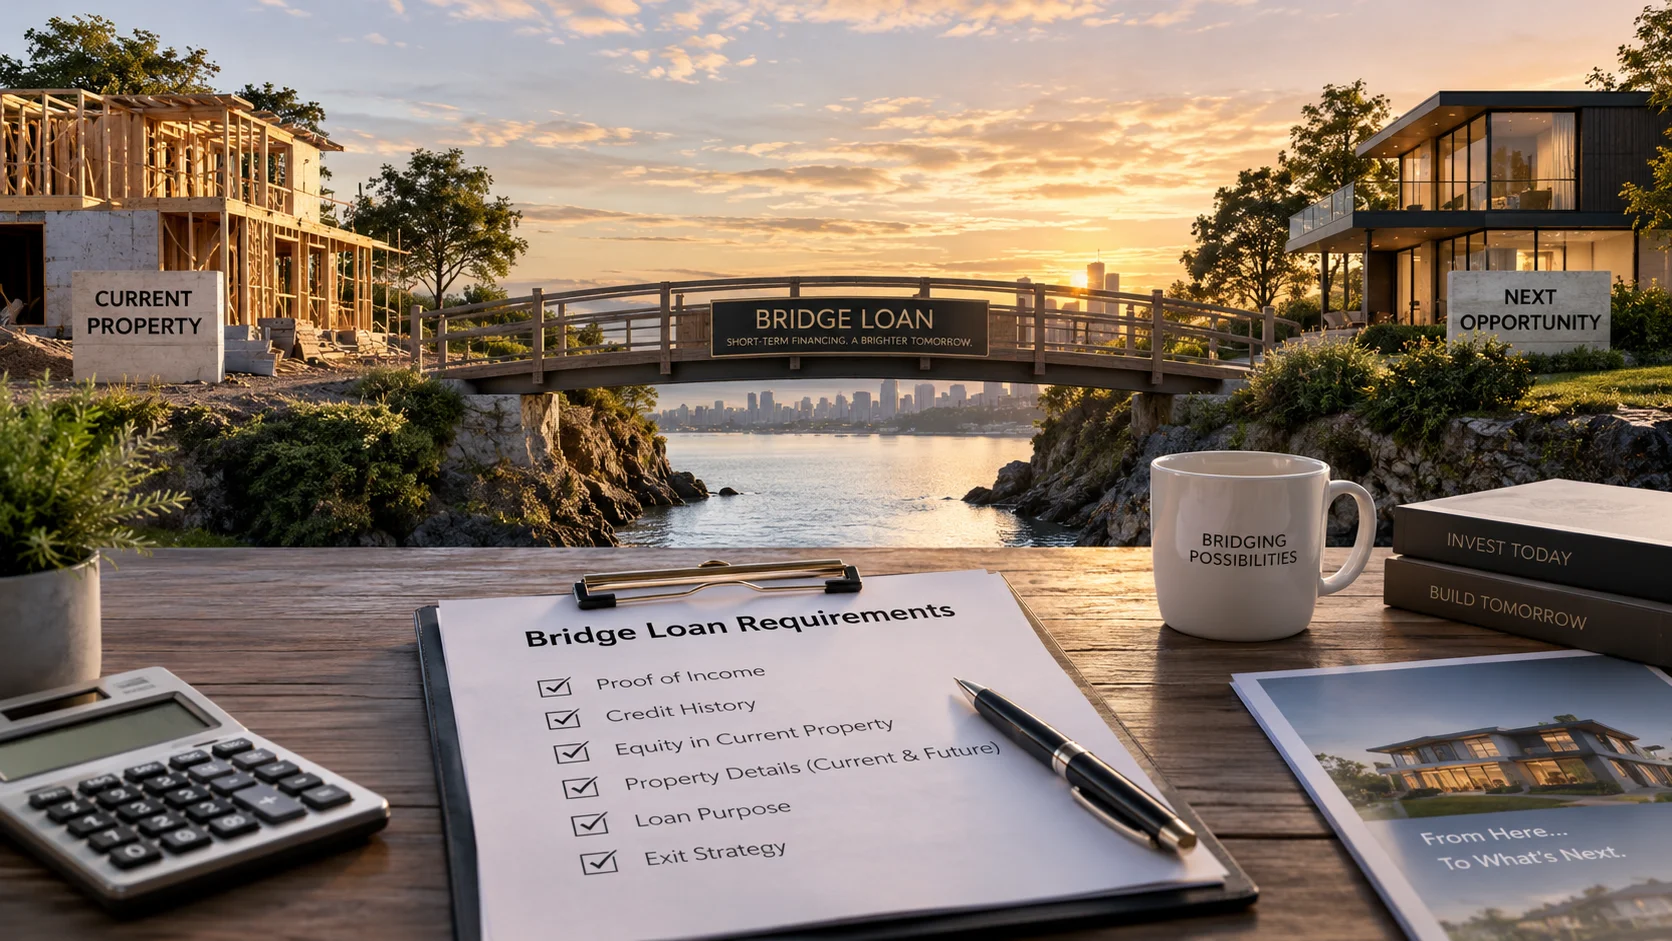
Documents Needed for a Bridge Loan
- A signed purchase contract on the new property
- The listing agreement or purchase contract for your current property
- A current mortgage statement showing your existing loan balance
- Proof of homeowners insurance
- Government-issued ID and Social Security verification
- An appraisal or broker price opinion on the departing property
How Do You Qualify for a Bridge Loan?
If you're wondering exactly how you qualify for a bridge loan, here's the process most borrowers go through:
- Calculate your available equity: Get a rough valuation on your current property and subtract what you still owe. This tells you roughly how much bridge financing you can access.
- Check your credit and DTI: Pull your credit report and calculate your DTI with the new bridge payment factored in before you apply, so there are no surprises.
- Gather your documentation: Income, assets, existing mortgage statement, and purchase contracts. The faster you provide these, the faster underwriting moves.
- Get pre-approved: A pre-approval tells you your realistic borrowing limit and strengthens any offer you make on the new property.
- Order the appraisal: Most lenders require a current appraisal on the property being used as collateral.
- Clear underwriting and close: Once your file is complete, bridge loans typically move through underwriting faster than a standard 30-year mortgage because the approval hinges more heavily on equity and exit strategy than on long-term income projections.
Bridge Loan Qualifications by Loan Type
What is the maximum LTV for a bridge loan?
Most lenders cap the loan-to-value ratio on the departing property between 65% and 80%, depending on property type, occupancy, and whether it's a primary residence or an investment property. Investment property bridge loans often sit at the more conservative end of that range since the lender is taking on collateral risk without an owner-occupant's added incentive to keep payments current.
How much can you borrow with a bridge loan?
In practice, your maximum loan amount is whichever is lower: the LTV cap applied to your current property's value, or the amount needed to cover the down payment and closing costs on the new purchase. Some lenders also offer a bridge-to-DSCR structure for investors, where the bridge loan funds the acquisition and closing, and a DSCR loan later refinances the property based on its rental income.
Do You Need an Appraisal for a Bridge Loan?
In almost all cases, yes. Because the loan amount is tied directly to your current property's value, lenders need a recent, independent valuation to confirm how much equity is actually available. Some lenders will accept a broker price opinion (BPO) or automated valuation model (AVM) for smaller loan amounts, but a full appraisal is standard for most bridge transactions.
Can You Get a Bridge Loan If You Still Have a Mortgage?
Yes, this is precisely the scenario bridge loans are designed for. You don't need to have sold, or even listed, your current property to qualify, though having it listed or under contract strengthens your application and can improve your DTI calculation. Lenders simply factor your existing mortgage payment into their underwriting alongside the new bridge payment, which is why sufficient income, reserves, and equity all matter so much here. The bridge loan sits in a second-lien position behind your existing mortgage until the current property sells and the bridge loan is paid off.
What Factors Can Cause a Bridge Loan Application to Be Denied?
The most common reasons bridge loan applications get denied include:
- Insufficient equity in the current property to support the requested loan amount at the lender's maximum LTV
- DTI that's too high once both the existing mortgage and the new bridge payment are factored in
- Incomplete or inconsistent documentation, especially for self-employed borrowers
- An unrealistic exit strategy, for example, listing a property well above market value with no price reduction plan
- Low appraisal value on the departing property that reduces available equity below what's needed
- Recent derogatory credit events, such as late mortgage payments in the last 12 months
How Long Does It Take to Get Approved for a Bridge Loan?
Bridge loans are built for speed. Once a complete application is submitted, many lenders can issue an approval within a few business days and close within one to three weeks. Bridge loans are considerably faster than the 30-to-45-day timeline typical of conventional mortgages. The biggest variable is how quickly you can supply documentation and how fast the appraisal on your current property can be scheduled.
Repayment and Exit Strategy Requirements
Because bridge loans are short-term, lenders require a clear, credible exit strategy and a plan for how you'll pay off the loan. The two most common exit strategies are:
- Sale of the current property, with proceeds used to pay off the bridge loan at closing
- Refinance into permanent financing, such as a DSCR loan or conventional mortgage, once the new property is stabilized or the borrower's financial picture changes
Lenders will often ask for evidence supporting your exit strategy as part of underwriting. Some bridge loans are structured as interest-only with a balloon payment due at maturity, so understanding your repayment timeline before you sign is essential.
Is a Bridge Loan Right for You?
A bridge loan isn't the cheapest form of financing, rates and fees run higher than a standard mortgage because you're paying for speed and flexibility. But for investors who can't afford to lose a deal while waiting on a sale, or homeowners who don't want to make a contingent offer in a competitive market, it can be the difference between getting the property and watching someone else close on it first.
The requirements are more about equity and exit strategy than perfect credit, which makes bridge loans accessible to borrowers who might not fit the box on a conventional loan. If your numbers are close but you're not sure where you land, that's exactly what a conversation with a loan officer is for.
Conclusion
Bridge loan requirements come down to five things: equity, credit, DTI, documentation, and a believable exit strategy. Borrowers who prepare their paperwork and know their numbers before applying move through underwriting fastest and avoid the most common reasons applications get denied.
If you're weighing a bridge loan against your next purchase, see how Rize Mortgage's bridge loan program works and talk to a loan officer about whether your equity and timeline line up.
What are the basic requirements for a bridge loan?
Most lenders look for at least 20–30% equity remaining in your current property, a credit score in the mid-600s or higher, a manageable DTI ratio even with both mortgage payments factored in, and a clear plan for paying off the loan.
How do you qualify for a bridge loan with an existing mortgage?
You can qualify even while carrying your current mortgage. Lenders factor that payment into your DTI alongside the new bridge payment, so your income and reserves need to support both until the loan is repaid.
What credit score is needed for a bridge loan?
Most lenders want a minimum score in the mid-600s, though a score of 700 or above typically qualifies you for better rates and terms.
How much can you borrow with a bridge loan?
Your borrowing limit is generally set by your lender's maximum loan-to-value ratio applied to your current property's appraised value, minus what you still owe on it.
Do you need an appraisal for a bridge loan?
Yes, in nearly all cases. Lenders need a current, independent valuation of your existing property to confirm how much equity is available to secure the loan.
Start your mortgage journey with clear guidance and real numbers. See what you qualify for today.